Company Base OS · The Fundable Business
The 30 Best Level 2 Business Rewards Cards, Compared (Chase, Amex, Capital One, BofA, U.S. Bank, Citi, PNC & Wells Fargo)
We researched 30 traditional bank-issued business rewards cards — the "Level 2" tier most businesses graduate to after fintech charge cards — and compared fees, bonuses, rewards, and what each issuer actually confirms about credit reporting.
CompanyBase Team
Updated November 17, 2026 · 14 min read
In this article
Last verified: November 18, 2026
This hub compares 30 cards researched directly against issuer pages (Chase, American Express, Capital One, Bank of America, U.S. Bank, Wells Fargo, Citi, and PNC), cross-checked against NerdWallet, The Points Guy, and Doctor of Credit. Welcome bonuses and APR ranges change often — each individual card review linked below has the full detail and verification notes.
If you have already looked at the no-personal-guarantee fintech charge cards on this site — Brex, Ramp, Mercury, and similar — this is the next tier up: the traditional, bank-issued business credit cards that most companies eventually carry alongside or instead of those. We call this "Level 2" because the underwriting model is fundamentally different. Every card below requires a personal guarantee and runs on your personal credit, in exchange for real rewards: points, miles, cash back, travel perks, and in some cases a genuine 0% financing window.
We researched all 30 cards the same way we research everything on this site: starting from the issuer's own rates-and-fees pages, not marketing copy, and labeling every fact as issuer-confirmed, third-party-reported, or genuinely unconfirmed. That last category comes up a lot in this tier — more on that below.
The Single Most Important Thing to Understand About This Whole Category
All 30 cards require a personal guarantee
Not one card in this roundup skips the personal guarantee. Chase, Amex, Capital One, Bank of America, U.S. Bank, Wells Fargo, Citi, and PNC all underwrite their business rewards cards against your personal credit, and you are personally liable for the balance regardless of how the application is framed. If avoiding that is your priority, [the no-personal-guarantee charge card hub](/blog/best-business-charge-cards-no-personal-guarantee) is the category you actually want.
The second thing worth knowing up front: across all 30 cards, bureau reporting to Dun & Bradstreet, Experian Business, or Equifax Business specifically is almost never confirmed by the issuer. Capital One is the one real exception — its own help-center content states, card by card, whether routine activity reports to personal bureaus. Every other issuer in this list is vague at best. If a verifiable, bureau-reporting business credit file is the actual goal, net-30 and net-60 vendor accounts still come first — these rewards cards are a spending tool layered on top of that foundation, not a substitute for it.
All 30 Cards at a Glance
| Card | Annual Fee | Best For |
|---|---|---|
| [Chase Ink Business Preferred](/blog/chase-ink-business-preferred) | $95 | 3x on ads, shipping, travel |
| [Chase Ink Business Cash](/blog/chase-ink-business-cash) | $0 | 5% office supplies & utilities |
| [Chase Ink Business Unlimited](/blog/chase-ink-business-unlimited) | $0 | Flat 1.5%, zero complexity |
| [Chase Ink Business Premier](/blog/chase-ink-business-premier) | $195 | 2.5% on $5,000+ purchases |
| [Amex Business Gold](/blog/amex-business-gold) | $375 | Auto 4x on your top 2 categories |
| [Amex Business Platinum](/blog/amex-business-platinum) | $895 | Lounge access, heavy travelers only |
| [Amex Blue Business Plus](/blog/amex-blue-business-plus) | $0 | Simple 2x up to $50K/yr |
| [Capital One Spark Cash Plus](/blog/capital-one-spark-cash-plus) | $150 (refundable) | Flat 2%, charge-card style |
| [Capital One Spark Cash Select](/blog/capital-one-spark-cash-select) | $0 | Flat 1.5% with real intro APR |
| [Capital One Venture Business](/blog/capital-one-venture-business) | $95 | Transferable miles, no personal-bureau reporting |
| [Capital One VentureOne Business](/blog/capital-one-ventureone-business) | $0 | No-fee entry into Capital One miles |
| [Capital One Spark Classic](/blog/capital-one-spark-classic) | $0 | Fair-credit entry point |
| [Capital One Venture X Business](/blog/capital-one-venture-x-business) | $395 | Huge bonus, huge spend requirement |
| [U.S. Bank Business Shield Visa](/blog/us-bank-business-shield-visa) | $0 | 12 months at 0% APR, not really "rewards" |
| [U.S. Bank Triple Cash Rewards](/blog/us-bank-business-triple-cash-rewards) | $0 | 3% + $100/yr software credit |
| [U.S. Bank Business Altitude Connect](/blog/us-bank-business-altitude-connect) | $0 yr1, then $95 | 4x travel & gas, no FX fee |
| [U.S. Bank Business Leverage](/blog/us-bank-business-leverage-visa-signature) | $0 yr1, then $95 | Auto 2x on your top 2 of 48 categories |
| [BofA Unlimited Cash Rewards](/blog/bofa-business-advantage-unlimited-cash-rewards) | $0 | Flat 1.5%, boosted by Preferred Rewards |
| [BofA Travel Rewards](/blog/bofa-business-advantage-travel-rewards) | $0 | Flat 1.5x points, no FX fee |
| [BofA Customized Cash Rewards](/blog/bofa-business-advantage-customized-cash-rewards) | $0 | Pick-your-category, up to 5.25% boosted |
| [Wells Fargo Signify Business Cash](/blog/wells-fargo-signify-business-cash) | $0 | Flat 2%, domestic spend only |
| [Citi Costco Anywhere Visa Business](/blog/citi-costco-anywhere-visa-business) | $0 + Costco membership | Costco members, no FX fee |
| [Citi AAdvantage Business](/blog/citi-aadvantage-business-card) | $99 (rising to $150) | American Airlines loyalty |
| [PNC Business Cash Rewards](/blog/pnc-business-cash-rewards-visa) | $0 | Easy $400 bonus on $3K spend |
| [PNC BusinessOptions](/blog/pnc-businessoptions-visa) | $0 | Big $800 bonus, in-branch only |
| [United Business Card](/blog/united-business-card-chase) | $150 | Free bag + United Club passes |
| [Southwest Rapid Rewards Performance](/blog/southwest-rapid-rewards-performance-business) | $299 | Group travel, path to Companion Pass |
| [Delta SkyMiles Platinum Business](/blog/delta-skymiles-platinum-business-amex) | $350 | Companion certificate, no Sky Club |
| [Marriott Bonvoy Business](/blog/marriott-bonvoy-business-amex) | $125 | Annual free night, Gold status |
| [Hilton Honors Business](/blog/hilton-honors-amex-business) | $195 | 12x at Hilton, no free-night award |
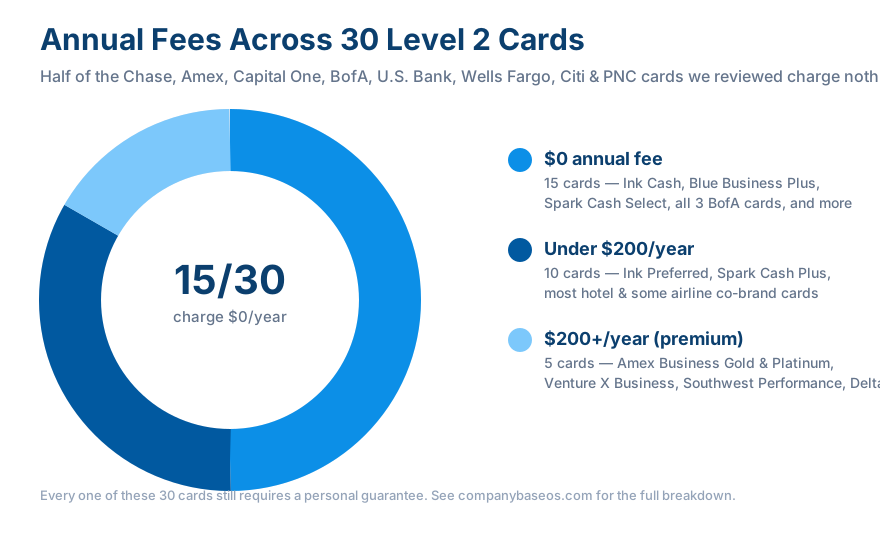
30
cards researched directly against issuer pages
30/30
require a personal guarantee
15
charge $0 annual fee
Free guide · instant access
The Business Foundation Checklist
Seven foundation mismatches that quietly cause automatic declines, and the fix for each.
How to Actually Choose Between These
Start with your spend pattern, not the bonus. A $895 card with $3,600 in potential credits is worthless to a business that doesn't travel; a $0 flat-rate card is a weak choice for a business running $200,000 a year through one dominant category. Match the card to what you already spend, not to the biggest headline number.
Then check what the issuer actually confirms, not what the marketing implies. Capital One is unusually direct about personal-bureau reporting, card by card. Chase's own documented exceptions mean its "generally doesn't report to personal bureaus" language is softer than it sounds. Amex claims business-bureau reporting that cardholders and forums repeatedly dispute. None of these 30 cards should be your primary strategy for building a scored, bureau-verified business credit file — that is what net-30 and net-60 vendor accounts are for, and what the different levels of business credit walks through in order.
Before You Apply to Any of These 30 Cards, Know Where You Stand
A hard inquiry is a hard inquiry. Most businesses applying for cards like these have never actually checked their fundability — the gaps in their bureau files that decide approval odds and starting limits before rewards even matter.
Get My Free Fundability ScoreLevel 1 vs. Level 2: What Actually Changes
| Level 1 (fintech charge cards) | Level 2 (this list) | |
|---|---|---|
| Underwriting | Business cash flow, funding, banking history | Personal credit + personal guarantee |
| Personal credit pull | Usually none (identity verification only) | Yes, on every card researched |
| Rewards depth | Thin — mostly a flat cashback/points rate | Deep — categories, travel perks, lounge access, co-brand loyalty |
| Bureau reporting clarity | A few vendors confirm directly (e.g. Brex, Ramp) | Almost never confirmed by name; Capital One is the exception |
| Typical starting point | New business, thin personal credit, wants to avoid PG | Established business, solid personal credit, wants real rewards |
Most businesses eventually use both tiers for different jobs: a Level 1 charge card for day-to-day operating spend with no personal exposure, and a Level 2 card layered on top once personal credit is strong enough to make the rewards worth the guarantee. See the Level 1 no-personal-guarantee charge card hub if you haven't already compared that tier.
Frequently asked questions
Do any of these 30 cards skip the personal guarantee?
No. Every card in this roundup requires one, whether or not the issuer uses that exact term in its marketing. For cards that genuinely skip it, see the Level 1 fintech charge card hub.
Which of these cards is best for building business credit specifically?
None of them should be your primary strategy for that. Bureau reporting to D&B, Experian Business, or Equifax Business is almost never confirmed by name across this entire category. Net-30 and net-60 vendor accounts remain the more reliable foundation.
Which card has the best welcome bonus?
It depends entirely on your realistic spend. Capital One Venture X Business advertises up to 300,000 miles, but requires $120,000 in spend within 4 months to earn the full amount — a bonus most small businesses will never fully capture. Match the spend requirement to your actual volume before chasing the biggest number.
Is a $0 annual fee card always the better choice?
Not necessarily. A $0 fee card with a lower earning rate can cost more over a year of heavy spend than a fee-based card with a stronger multiplier. Run the math on your actual annual spend in each card's bonus categories before deciding on fee alone.
Find out where you actually stand in 60 seconds
Take the free Business Fundability quiz. Answer seven questions and get your score out of 100, your single biggest blocker, and the exact first move to fix it.
Get my free Fundability ScoreCompany Base OS
Stop reading about it. Get your exact next move.
CompanyBase reads your business credit file and hands you the one account to open next, and the exact day to apply. Start with your free Fundability Score.
Get my free Fundability Score →60 seconds · no credit pull · founding access just $7 today
CompanyBase Team
Company Base OS is an educational platform that helps business owners build business credit and get funded, in the right order. Our team tracks lender and bureau criteria so you always know your exact next move.